
Business Loan Finance Online :: News
SHARE

Share this news item!

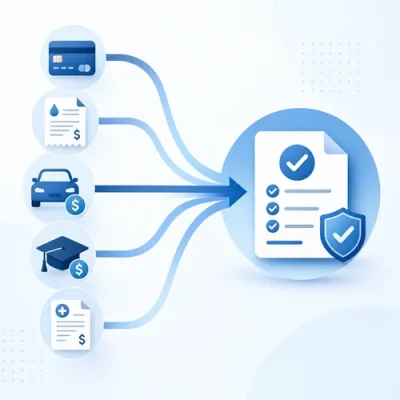
Why More Australians Are Rechecking Their Debt Mix

Simpler repayments can help, but only when the full cost is clear

Why More Australians Are Rechecking Their Debt Mix?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Recent consumer finance reporting has again highlighted a familiar pressure point for Australian households: managing several debts at once can become harder as everyday costs stay elevated.
Credit cards, buy now pay later balances, car repairs, medical bills and overdue utilities can each look manageable in isolation, but together they may create a repayment calendar that is difficult to keep under control.

That is why debt consolidation is getting renewed attention. The idea is straightforward: replace multiple repayments with one new loan, ideally with a clearer schedule and a lower overall cost. For borrowers considering small loans, this can sound appealing, particularly when cash flow is tight or when missed payments are starting to affect confidence.

However, consolidation is not automatically a cheaper outcome. A lower monthly repayment can sometimes come from stretching the debt over a longer term, which may increase the total interest paid. Establishment fees, monthly account fees, early payout costs and comparison rates also matter. Before applying, borrowers should estimate repayments under different terms rather than focusing only on the headline rate.

For people with irregular income, casual work, self-employment or a patchy credit history, the assessment may also be more detailed. Lenders may review income consistency, bank statements, existing commitments and recent repayment behaviour. These responsible lending checks are designed to test whether the new loan is suitable and affordable, not just whether the borrower wants to simplify their finances.

A practical starting point is to list each current debt, including the balance, interest rate, fees, minimum repayment and due date. Then compare that total with the proposed new loan amount, repayment term and total cost. If the new loan clears expensive debt but leaves the borrower relying on credit cards again for groceries or rent, the problem may be budget pressure rather than loan structure.

Debt consolidation can still be useful when it is part of a wider plan. That may include closing or reducing unused credit limits, setting up payment reminders, building a small emergency buffer and seeking hardship support early if income changes. For small business owners, the same thinking applies: using finance to tidy short-term obligations should be weighed against upcoming tax, wages, stock and seasonal cash flow needs.

The key message is not to rush. A small loan can provide structure and breathing room, but it should leave the borrower in a stronger position after fees, interest and repayments are fully understood.

Published:Wednesday, 16th Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

What a Steady Rate Setting Means for Boat Buyers
17 Sep 2026: Paige Estritori
The Reserve Bank’s latest decision to keep the cash rate steady gives Australian boat buyers a useful moment to pause, but it should not be mistaken for a guarantee that borrowing costs will stay simple or uniform. For households looking at a first trailer boat, a fishing upgrade, a personal watercraft or a larger family cruiser, the lending market remains highly dependent on borrower profile, boat type, deposit size, loan structure and lender appetite. - read more
Why hardship support is now a bigger loan issue
17 Sep 2026: Paige Estritori
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more
Card Spending Trends Keep Personal Loan Planning in Focus
17 Sep 2026: Paige Estritori
The Reserve Bank of Australia’s latest retail payments update offers another useful snapshot of how households are managing everyday spending, card use and short-term credit. While payment data is not the same as loan approval data, it can still tell borrowers something important: the way money moves through a household each month can affect how comfortable a lender feels about future repayments. - read more
Why Online Caravan Listings Need More Care Before You Pay
17 Sep 2026: Paige Estritori
Fresh consumer warnings about online vehicle scams are a timely reminder for caravan buyers to slow down before transferring deposits, sharing identity documents or arranging settlement. Caravans, camper trailers and motorhomes are high-value assets, and that makes them attractive targets for fake listings, cloned advertisements and sellers who pressure buyers to act quickly. - read more


Business Loans Articles

Working Capital Finance and Business Lines of Credit Explained
Working capital finance and business lines of credit can help Australian businesses manage short-term cash flow needs, seasonal expenses and timing gaps between income and outgoings. This guide explains how these facilities work, how they differ from standard business loans, and what to consider before applying. - read more
Business Loan Costs in Australia: Interest, Fees and Repayment Factors Explained
Business loan costs can include more than the advertised interest rate. Learn how interest, fees, loan term, repayment frequency and facility structure can affect total repayments in Australia. - read more
Building a Strong Business Plan: The Key to Securing Financing
In the vibrant world of startups, securing funding is often the key to turning a business idea into a reality. For Australian entrepreneurs, understanding the landscape of available financial resources is crucial. Whether you're launching a tech startup in Sydney or opening a new café in Melbourne, accessing capital can be a deciding factor in your venture's success. - read more
Understanding Lenders: What They Look for in Your Loan Application
Applying for a small business loan can feel overwhelming, but with the right preparation, you can improve your chances of success significantly. Understanding what lenders look for in a loan application is crucial to making your business stand out. - read more


Free Assessment

Loan Amount:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Truth in Lending Act (TILA):
A federal law designed to promote the informed use of consumer credit by requiring disclosures about terms and costs.