Electronic Tags Put Livestock Gear Back on the Budget
Compliance, handling efficiency and cash flow now need to be planned together
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
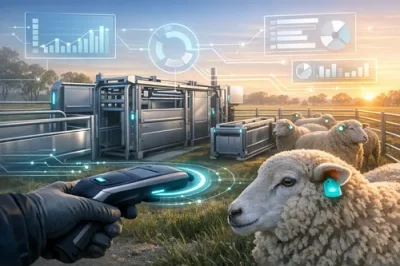
Recent rural coverage of the national sheep and goat electronic identification rollout is a timely reminder that compliance changes can quickly become machinery decisions.
For many producers, eID is not only about tags.
It can also involve scanners, panel readers, weigh systems, drafting equipment, race upgrades, software subscriptions and better connectivity around yards and loading areas.
The finance issue is that these costs do not always arrive neatly in one purchase. A farm may start with a handheld reader, then discover that labour savings and data quality improve when the system is connected to scales, auto-drafting or updated yards. For larger livestock operations, that can turn a compliance expense into a broader productivity investment.
Farm businesses should also be careful about matching the finance structure to the useful life of each asset. Portable readers and software may have a shorter upgrade cycle than steel yards, weigh crates or fixed handling infrastructure. Bundling everything into one facility can be convenient, but the repayment term, residual value and ownership outcome should still make sense for the way the equipment will be used.
Cash flow timing matters as well. Sheep and goat producers often work around joining, marking, shearing, selling and seasonal feed costs. If eID-related investment is being made ahead of a key sale period, repayments need to sit comfortably beside freight, contractor, animal health and labour expenses. Before committing, it may help to estimate repayments under different deposit, trade-in, term and balloon scenarios.
Government support programs may reduce the outlay in some states, but producers should check whether assistance is paid upfront or by reimbursement, and whether grant timing matches the supplier’s payment terms. A delayed rebate can still leave a temporary working capital gap, particularly where multiple sites or large mobs require extra readers or yard upgrades.
The practical takeaway is to treat eID preparation as both a compliance task and a capital planning exercise. Producers who map their current handling process, identify bottlenecks and separate must-have equipment from efficiency upgrades are likely to make clearer decisions. The cheapest reader may satisfy the immediate rule, but the right integrated system could also reduce labour pressure, improve livestock data and support better sale decisions over time.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
The Reserve Bank’s latest decision to keep the cash rate steady gives Australian boat buyers a useful moment to pause, but it should not be mistaken for a guarantee that borrowing costs will stay simple or uniform. For households looking at a first trailer boat, a fishing upgrade, a personal watercraft or a larger family cruiser, the lending market remains highly dependent on borrower profile, boat type, deposit size, loan structure and lender appetite. - read more
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more
The Reserve Bank of Australia’s latest retail payments update offers another useful snapshot of how households are managing everyday spending, card use and short-term credit. While payment data is not the same as loan approval data, it can still tell borrowers something important: the way money moves through a household each month can affect how comfortable a lender feels about future repayments. - read more
Fresh consumer warnings about online vehicle scams are a timely reminder for caravan buyers to slow down before transferring deposits, sharing identity documents or arranging settlement. Caravans, camper trailers and motorhomes are high-value assets, and that makes them attractive targets for fake listings, cloned advertisements and sellers who pressure buyers to act quickly. - read more
Secured and unsecured business loans differ mainly in whether the borrower offers assets as security. This guide explains collateral, personal guarantees, lender risk assessment and key questions Australian business owners should consider before applying. - read more
Working capital finance and business lines of credit can help Australian businesses manage short-term cash flow needs, seasonal expenses and timing gaps between income and outgoings. This guide explains how these facilities work, how they differ from standard business loans, and what to consider before applying. - read more
Creating a compelling pitch is crucial for any entrepreneur seeking to attract investors. It's more than just presenting numbers and forecasts; it's about connecting on a human level and conveying your vision effectively. - read more
Applying for a small business loan can feel overwhelming, but with the right preparation, you can improve your chances of success significantly. Understanding what lenders look for in a loan application is crucial to making your business stand out. - read more
Knowledgebase
Second Mortgage: A type of subordinate mortgage made while an original mortgage is still in effect.



No comments yet. Be the first to share your thoughts.