
Business Loan Finance Online :: News
SHARE

Share this news item!

Why Hardship Complaints Matter When Debt Feels Unmanageable

Early action can protect cash flow, credit health and future borrowing options

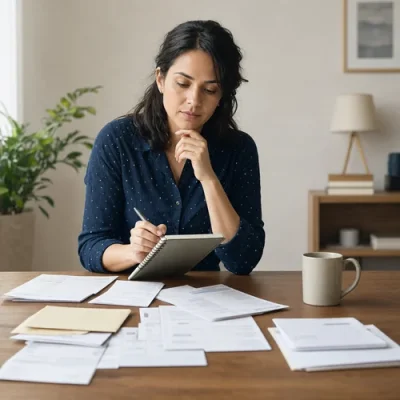
Why Hardship Complaints Matter When Debt Feels Unmanageable?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Fresh financial complaints reporting has again highlighted a difficult reality for many Australian households: when repayments start to fall behind, the problem is rarely limited to one bill.
Mortgage stress, credit card balances, personal loans, car finance, buy now pay later commitments and utility arrears can all collide at once, leaving borrowers unsure which creditor to call first or what support they are entitled to request.

The key message for anyone under pressure is that hardship is not a personal failure. It is a formal process lenders and credit providers are expected to consider when a customer cannot meet repayments because of illness, reduced income, job loss, family changes or rising living costs. The earlier a borrower asks for help, the more options may be available, including temporary payment pauses, reduced repayments, extensions of loan terms or tailored arrangements to catch up over time.

For Australians juggling several unsecured debts, this matters because missed payments can quickly create a chain reaction. A late credit card payment may trigger fees and interest. A personal loan arrears notice can add stress to an already tight budget. If multiple creditors are involved, keeping track of due dates and hardship conversations can become overwhelming.

Debt consolidation loans may help some borrowers simplify the picture by combining several debts into one repayment, but they are not a cure-all. The real test is whether the new structure reduces financial pressure without increasing the total cost over the long term. A lower monthly repayment can be useful for cash flow, but a longer loan term may mean paying more interest overall.

Before making a decision, borrowers should list every debt, including balances, interest rates, fees, minimum repayments and arrears. It can also help to estimate repayments and total costs under different scenarios, especially if considering a consolidation loan, refinancing option or repayment plan.

Anyone already behind should also understand the difference between consolidation, hardship arrangements and more serious debt relief options. Consolidation usually requires enough income to afford a new loan. Hardship assistance may be more suitable when the issue is temporary. Formal debt agreements or insolvency pathways can carry significant credit and legal consequences, so they should not be entered into lightly.

The practical takeaway is to act before the pressure becomes unmanageable. Open letters and lender emails, write down who you owe, contact creditors early, and keep records of every conversation. Clear information gives you more control and can help turn a stressful pile of repayments into a more structured plan.

Published:Tuesday, 1st Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

What a Steady Rate Setting Means for Boat Buyers
17 Sep 2026: Paige Estritori
The Reserve Bank’s latest decision to keep the cash rate steady gives Australian boat buyers a useful moment to pause, but it should not be mistaken for a guarantee that borrowing costs will stay simple or uniform. For households looking at a first trailer boat, a fishing upgrade, a personal watercraft or a larger family cruiser, the lending market remains highly dependent on borrower profile, boat type, deposit size, loan structure and lender appetite. - read more
Why hardship support is now a bigger loan issue
17 Sep 2026: Paige Estritori
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more
Card Spending Trends Keep Personal Loan Planning in Focus
17 Sep 2026: Paige Estritori
The Reserve Bank of Australia’s latest retail payments update offers another useful snapshot of how households are managing everyday spending, card use and short-term credit. While payment data is not the same as loan approval data, it can still tell borrowers something important: the way money moves through a household each month can affect how comfortable a lender feels about future repayments. - read more
Why Online Caravan Listings Need More Care Before You Pay
17 Sep 2026: Paige Estritori
Fresh consumer warnings about online vehicle scams are a timely reminder for caravan buyers to slow down before transferring deposits, sharing identity documents or arranging settlement. Caravans, camper trailers and motorhomes are high-value assets, and that makes them attractive targets for fake listings, cloned advertisements and sellers who pressure buyers to act quickly. - read more


Business Loans Articles

Building a Strong Business Plan: The Key to Securing Financing
In the vibrant world of startups, securing funding is often the key to turning a business idea into a reality. For Australian entrepreneurs, understanding the landscape of available financial resources is crucial. Whether you're launching a tech startup in Sydney or opening a new café in Melbourne, accessing capital can be a deciding factor in your venture's success. - read more
The Role of Government Grants in Financing Your Startup
Government grants can be a lifeline for startups seeking funds to launch or expand their businesses. These grants are sums of money provided by governmental bodies that do not require repayment, making them an attractive option for entrepreneurs. - read more
Understanding Lenders: What They Look for in Your Loan Application
Applying for a small business loan can feel overwhelming, but with the right preparation, you can improve your chances of success significantly. Understanding what lenders look for in a loan application is crucial to making your business stand out. - read more
How to Craft a Winning Pitch to Attract Investors
Creating a compelling pitch is crucial for any entrepreneur seeking to attract investors. It's more than just presenting numbers and forecasts; it's about connecting on a human level and conveying your vision effectively. - read more


Free Assessment

Loan Amount:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Mortgage Document:
The physical contract agreement that a Mortgagee (lender) enters into with a Mortgagor (borrower) outlining the precice terms of a mortgage loan.